Completion vs. draw mortgages — what's the difference?

There are two main ways to finance a new build in Alberta: a completion mortgage or a draw (progress-draw) mortgage. Your builder's contract usually points you toward one or the other, but it helps to understand both before you sign anything.

Completion Mortgages

With a completion mortgage, the full loan amount is advanced in one lump sum once your home is finished and you take possession — similar to how financing works on a resale home. Your builder carries the cost of construction, and you don't start making mortgage payments until you move in.

  • Access to listings: I have access to a wealth of listings, including homes that may not be publicly listed, giving you more options to choose from.

  • Expertise: I have a deep understanding of the market and can provide valuable insights and advice on factors like home values, negotiation strategies, and closing costs.

  • Negotiation skills: I am an experienced negotiator and can help you get the best deal on your new home.

  • Handling paperwork: The home-buying process involves a lot of paperwork, and I can help you navigate it all, from the offer to closing.

  • Stress relief: Buying a home can be stressful, but I can take some of the burden off by handling the logistics and communicating with other parties involved in the transaction.
Buying resources

Draw Mortgages

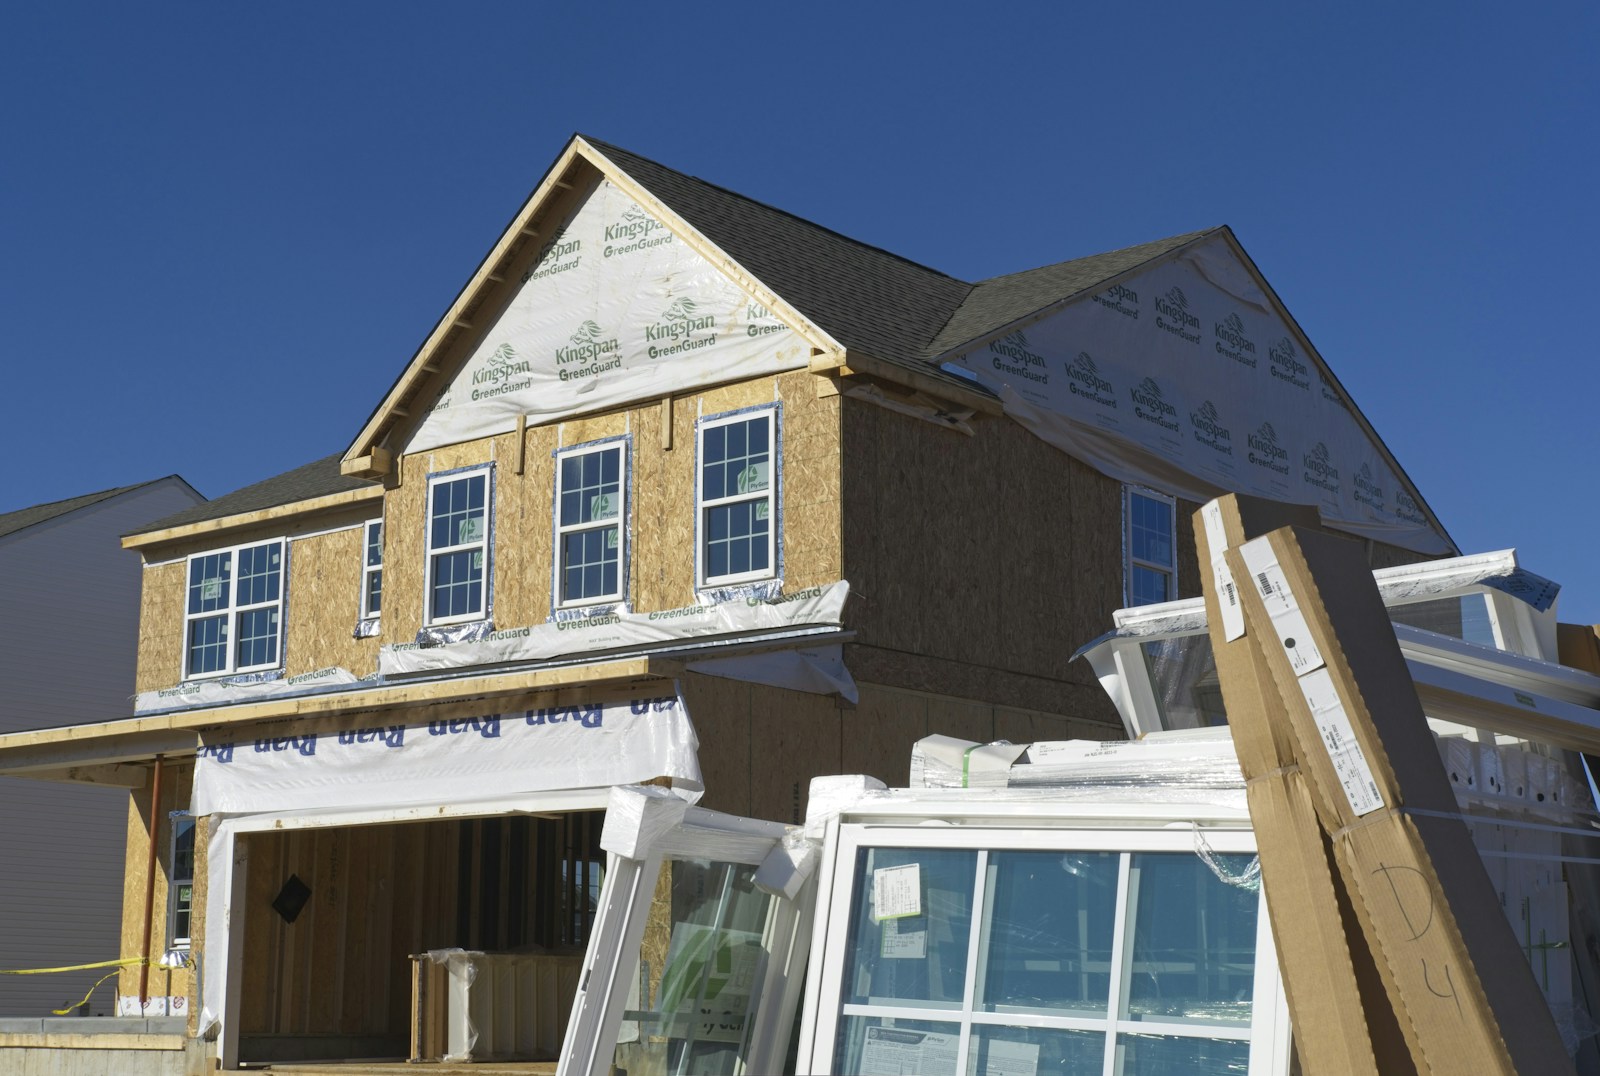
A draw mortgage releases funds in stages as construction hits agreed milestones — foundation, framing, and so on — with a lender-appointed appraiser confirming progress before each draw is released. This is the more common route if you're building on land you already own or working with a smaller custom builder.

Pros:

  • You only pay interest on the funds that have actually been drawn, not the full loan amount
  • Works for custom and owner-lot builds where a builder isn't self-financing

Cons:

  • More paperwork and coordination, with each draw requiring lender sign-off
  • Interest payments start during construction, before you're living in the home
  • Delays in inspections can hold up a draw and slow down progress


Extended rate holds for new builds

A standard mortgage pre-approval usually holds your rate for 90 to 120 days — plenty of time for a resale purchase, but not nearly enough for a build that could take 6, 12, or even 18 months to complete. That's where an extended rate hold comes in.

Many lenders offer new-build rate holds in the 6 to 12 month range (with some going longer, depending on your builder's timeline and the lender), which locks in your rate while your home is under construction. This can be very beneficial to have this in place in case rates were to increase over the timeline of your build.

We can help match your build timeline to a lender that offers a hold long enough to actually cover it, instead of finding out four months in that your rate has expired.

New Home Construction Builds vs Spec Home Purchases

Interested to learn more about new home construction builds vs spec home purchases? Ready to have a look at some listings?  Check out our other page for more info

Ready to make a move?

If you're not sure yet which situation you're in, that's a completely normal place to start — we can walk through everything with you, step by step & get a tailored plan in place

FAQ's

Our Team of professionals is here to guide you each step of the way

What's the difference between a draw mortgage and a completion mortgage?

A completion mortgage pays out the full loan amount once your home is finished and you take possession. A draw mortgage releases funds in stages as construction hits key milestones, with an inspection required before each release.

Which one should I choose for my new build?

It often depends on your builder's contract & processes. Builders financing the construction themselves usually offer a completion mortgage; if you're building on your own lot or with a smaller custom builder, a draw mortgage is more common.

Do I make mortgage payments during construction?

With a completion mortgage, no — payments start once you take possession. With a draw mortgage, you typically pay interest on the funds drawn so far as construction progresses, before you're living in the home.

What is an extended rate hold, and do I need one?

It's a lender's commitment to hold your rate for longer than the standard 90 to 120 days — often 6 to 12 months for new builds. If your build won't be finished for several months, an extended hold protects you from rate increases while you wait.

What happens if interest rates change before my home is finished?

With a standard rate hold (eg 4 months), if your rate expires before closing, you'll requalify at whatever rates are available then. With an extended rate hold, the goal is for it to last long enough for your home to be finished.  We keep in touch during your build to know where the process is.

Can I switch lenders if my rate hold runs out before my home is complete?

Yes, though it means starting a new application and requalifying under current rates and lending rules. It's usually easier — and often cheaper — to secure the right length of rate hold from the start, but we work with you through all of these discussions.

Do I need a bigger down payment for a new build?

It depends on the lender and the mortgage type, but new construction financing sometimes requires a larger down payment than a resale purchase, particularly with draw mortgages. We can walk you through what a specific lender will require for your situation.

Can you represent me for my financing and as my Realtor for the build?

Yes, we often work with our clients for both their financing and real estate needs.

What if I own a home already and want to build a new house?

We come across this scenario often and need to work with you for the different options available. Once we have a mortgage application, then we can structure options tailored to you.

Data last updated on October 13, 2026 at 01:30 PM (UTC).
Copyright 2026 by the REALTORS® Association of Edmonton. All Rights Reserved.
Data is deemed reliable but is not guaranteed accurate by the REALTORS® Association of Edmonton.
The trademarks REALTOR®, REALTORS® and the REALTOR® logo are controlled by The Canadian Real Estate Association (CREA) and identify real estate professionals who are members of CREA. The trademarks MLS®, Multiple Listing Service® and the associated logos are owned by CREA and identify the quality of services provided by real estate professionals who are members of CREA.